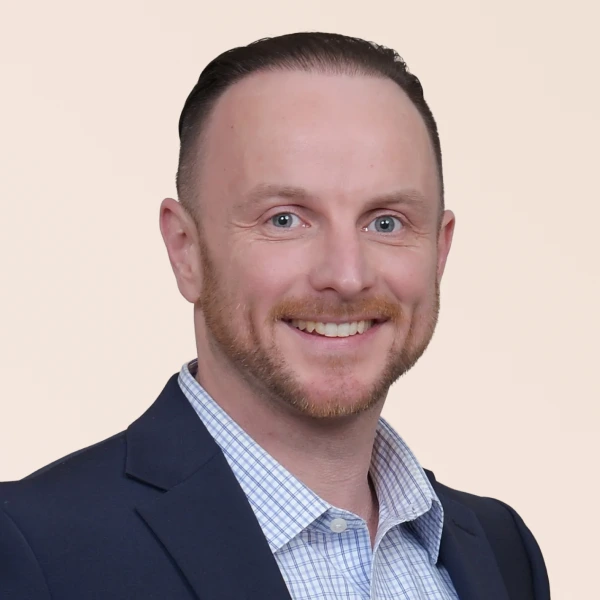

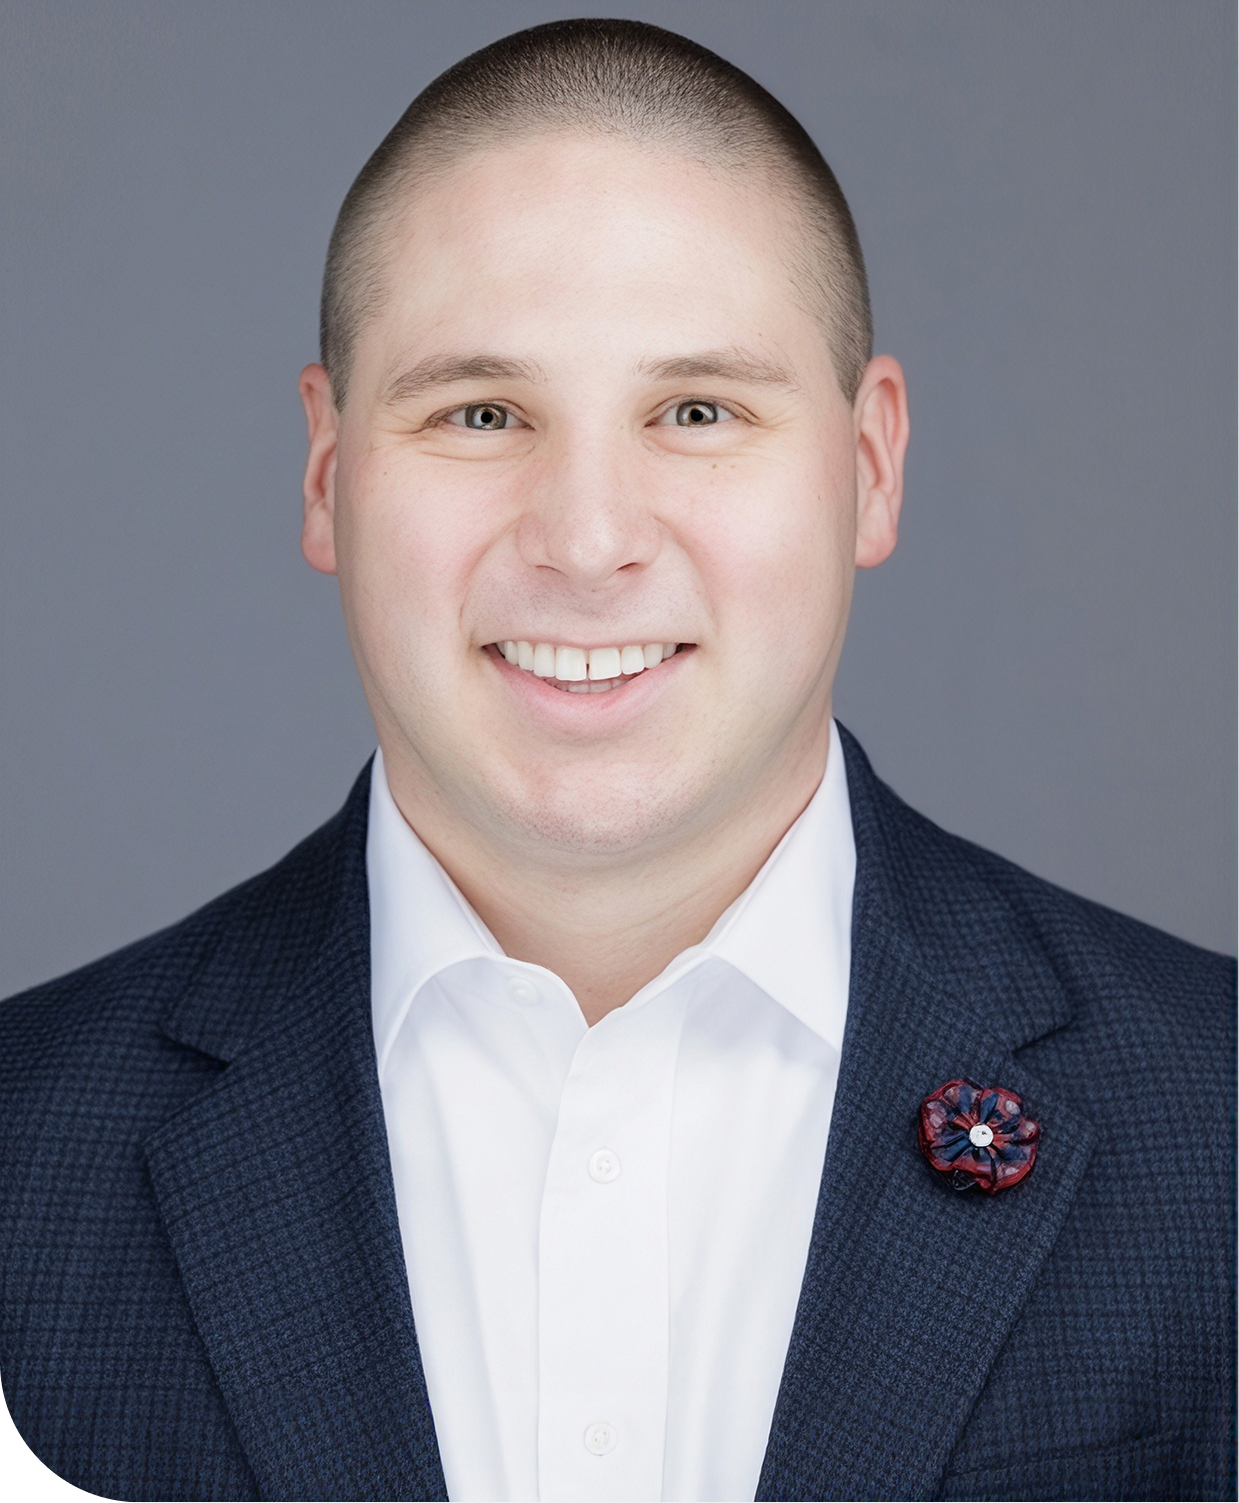
Drew Harmon, CFP®, APMA®
Hi, I’m Drew. I’m a Wealth Manager based in Cincinnati, Ohio, with 12 years of experience helping individuals and couples make thoughtful decisions across their financial lives.
I work with high-earning professionals who are working to build wealth, as well as individuals and couples approaching or living in retirement. My approach brings together retirement planning, tax planning, income planning, investment management, estate and legacy considerations, and risk management so clients can understand how each financial decision fits into the bigger picture.
Whether you are determining how much to save, evaluating a Roth conversion, preparing for retirement, or developing a plan for your family and legacy, my goal is to help you make informed decisions with a clear financial framework.

Cincinnati, OH


“I take a comprehensive approach to financial planning, helping clients connect their investments, taxes, retirement income, estate considerations, and risk management into one coordinated financial plan.”
How can I help?
Retirement Planning

Financial Planning & Analysis
Personalized wealth management helps our clients protect their assets. We use a holistic approach to financial planning that integrates tax strategy, trust & estate planning, and risk management.

Tax Optimization
We aim to take the ambiguity out of tax planning by utilizing tax-reducing strategies that encompass your overall tax liability. We do it by putting together a game plan that is specific to your needs.

Income Planning
Understand your income with an annual plan showing where cash flow is generated, and why. This weaves together Restricted Stock Units (RSU) flows, stock option exercises, long-term capital gains, Roth Conversions, etc.

Get to know Drew
Drew Harmon, CFP®, APMA®, is a Wealth Manager at Savvy with 12 years of experience in financial services. He works with high-earning young professionals and couples who are working to build wealth, along with individuals and couples who are nearing or already in retirement.
Drew graduated from the University of Cincinnati Carl H. Lindner College of Business in 2014 with degrees in Finance and Entrepreneurship. He began his financial services career that same year and joined a small registered investment adviser in Sharonville, Ohio, before moving to Ameriprise Financial in 2015. He joined Savvy Wealth in September 2026.
His planning work focuses on helping clients coordinate the many parts of their financial lives. For younger professionals and couples, that can include budgeting, retirement savings, investment management, tax planning, insurance considerations, and estate planning. For clients approaching or living in retirement, Drew often focuses on retirement income, Roth conversions, investment management, tax planning, and legacy considerations.
Drew believes financial planning is most useful when each decision is viewed as part of a connected system. Rather than addressing investments, taxes, estate considerations, or risk management in isolation, he helps clients evaluate how those areas interact and how their decisions can support their broader financial and life goals.
He holds the CERTIFIED FINANCIAL PLANNER™ certification and the Accredited Portfolio Management Advisor℠ designation.
I graduated from the University of Cincinnati in 2014 with degrees in Finance and Entrepreneurship. Shortly after graduating, I joined a small registered investment adviser in Sharonville, Ohio. That experience gave me an early opportunity to work in financial planning and see how thoughtful advice can affect a client’s financial life.
In December 2015, I joined Ameriprise Financial, where I continued developing my approach to planning and working directly with clients. Over the course of my career, I’ve become increasingly focused on bringing investments, taxes, retirement planning, estate considerations, and risk management together within one coordinated process.
Ever since I was a kid, I've been fascinated by the stock market. Growing up, I would watch CNBC with my dad. During my freshman year of high school, I listened to a financial advisor present during career day and figured that's what I wanted to do for my career. Throughout my college career, I co-oped at GE Aerospace then a money management firm, and finally, a financial planning firm. Through my co-ops, I realized I wanted to work with investments and helping people.
Two areas I spend a significant amount of time on are tax planning and retirement income planning.
Tax decisions can affect many parts of a financial plan, so I look at how taxes connect with investment decisions, retirement accounts, Roth conversions, and income needs. For clients nearing or living in retirement, I also focus on developing an organized approach to where income will come from and how different accounts can work together over time.
I primarily work with two groups. The first is high-earning young professionals and couples who are working to build wealth and want help making informed decisions about saving, investing, taxes, and their broader financial plan.
I also work with individuals and couples who are approaching or already in retirement and generally have at least $500,000 in investable assets. For these clients, our conversations often center on retirement income, taxes, investments, Roth conversions, and legacy planning.
I focus on tax planning and optimization because they are crucial aspects to consider when managing your finances. By strategizing efficient ways to minimize tax liabilities and maximize savings, my clients can plan for the future. Additionally, I also help clients with retirement planning, Investment management, and cash flow planning because they are essential for maintaining a healthy financial balance.
For younger clients, I often help with budgeting, determining how much to save for retirement, deciding which types of accounts to use, investment management, tax planning, insurance considerations, and estate planning.
For clients nearing or in retirement, I often help evaluate retirement income strategies, Roth conversions, investment management, tax considerations, and legacy planning.
The specific strategy depends on the client’s circumstances, priorities, and stage of life.
I use a comprehensive planning process designed to connect the different areas of a client’s financial life.
Investments are one part of that process, but I also consider taxes, retirement income, estate and legacy planning, and risk management. Looking at these areas together can help identify how one financial decision may affect another and give clients a more organized framework for evaluating their options.
My favorite part is seeing clients reach the financial and life goals they have been working toward.
It is rewarding to see someone move from planning for an important milestone to actually experiencing it, whether that means enjoying retirement, spending more time with family, or simply having greater clarity around their finances. I value being able to build relationships with clients and help them navigate those decisions over time.
I chose Savvy because I was looking for the right partner to support both my clients’ financial goals and the continued development of my practice.
Savvy provides technology, tools, and resources that allow me to spend more of my time focused on client relationships, financial planning, and helping clients make thoughtful decisions about their financial lives.
Book a 30-min introductory call with Joshua.
Meet and greet. Get to know each other and learn about the benefits of wealth management through Savvy.
Neither Savvy Wealth, nor Savvy Advisors compensates directly for testimonials or endorsements provided herein, by advisers. However advisors may have an indirect financial incentive to provide testimonials.